
Parex/ Frontera
Overview
Frontera, a TSX-listed corporation, is expected to sell, pursuant to a BC Plan of Arrangement, all of its Colombian oil and gas business to Parex Resources, an Alberta TSX-listed corporation. This would be accomplished through the sale of a Swiss holding company to an Alberta Buyco subsidiary of Parex. The consideration will consist of approximately US$500 million in cash, the assumption of unsecured notes in the amount of US$310 million, and a contingent payment of US$25 million if a Colombian authority agrees to extend a key agreement within one year of the completion of the Plan of Arrangement.
It is contemplated that, outside of the Plan of Arrangement, most of the US$500 million in cash will be distributed to Frontera shareholders as a return of capital. The US$25 million contingent payment, if received before the amount of the return of capital distribution is finalized by the Frontera Board of Directors, will also be included in the RoC distribution. Otherwise, that payment likely would be distributed as a dividend or through a share buyback. (S. 84(4.1)(b) requires that a sales proceeds PUC distribution must be made on a one-off basis.)
Following the above transactions, Frontera will continue to hold, through subsidiaries, significant infrastructure assets in Colombia.
Frontera
A British Columbia corporation listed on the TSX, holding oil and gas assets in Colombia through indirect subsidiaries of the Company, and also indirectly holding infrastructure assets in Columbia.
Company
Frontera Petroleum International Holdings BV, a Netherlands private company.
Parex
A corporation incorporated under the laws of Alberta that is the largest independent oil and gas producer in Columbia.
Purchaser
A corporation incorporated under the laws of Alberta.
Plan of Arrangement
Under a BC plan of arrangement:
- Each Frontera share held by a dissenting Frontera shareholder will be transferred to Frontera in consideration for a debt claim against Frontera based on the fair value of such Frontera shares.
- Each Company share will be transferred by Frontera to the Purchaser in consideration for an amount of cash equal to the closing payment described below.
- As part of the arrangement, unsecured notes for US$310 million due in June 2028, with a coupon rate of 7.875% and held by a third-party trustee, will be assumed by the Purchaser or a subsidiary thereof at the effective time of the arrangement as part of the purchase consideration.
Purchase Agreement
The purchase agreement for Frontera’s sale of the Company includes:
- A base purchase price of US$500 million, subject to adjustments.
- An additional contingent payment of US$25 million if the term of Frontera's contract in respect of the Quifa area is extended prior to the first anniversary of the completion of the arrangement.
Return of Capital
Frontera intends to make a cash distribution to its shareholders of up to approximately US$470 million, mostly or entirely as a return of capital. This amount is comprised of:
- A return of capital distribution of between US$445 million and US$455 million, funded out of the closing payment on the sale of the Company.
- An additional contingent payment of up to US$25 million, if the contingent payment is received.
The contingent distribution may be accomplished via a return of capital if the contingent payment is received prior to the final determination of the amount of the return of capital by the Frontera Board following the closing of the arrangement. Otherwise, it may be executed via share buybacks or a special dividend, subject to determination by the Frontera Board at the applicable time.
Frontera will issue a press release announcing the declaration of the return of capital if and when it is formally declared, along with the record date, payment date, and ex-distribution trading date therefor. Frontera anticipates that the TSX will implement “due bill” trading regarding the return of capital.
Frontera Post-Arrangement
Following the completion of the arrangement, Frontera will continue to hold infrastructure assets in Colombia, including:
- A 35% interest in a strategic crude oil pipeline.
- Most of a state-of-the-art maritime terminal.
Canadian Tax Considerations
Management expects that one of the exceptions to ITA s. 84 will apply to the return of capital distribution.
RWI Policy
60 days prior to the Arrangement Agreement date of March 10, 2026, the Purchaser shall use reasonable commercial efforts to obtain, and Frontera shall provide all reasonable cooperation in connection with, a buyer's side representations and warranties insurance (RWI) policy issued in the name of the Purchaser parties or any of their affiliates. This policy will cover the representations and warranties of Frontera made under the Arrangement Agreement, with coverage amounts no less than and retention amounts no greater than those set forth in the schedule to the Arrangement Agreement.
Strathcona
Overview
Strathcona intended to distribute $2.14 billion of the proceeds from the sale of its Montney assets. It determined that not all shareholders would prefer to receive the distribution as a PUC distribution rather than as a taxable dividend. Accordingly, shareholders were given the choice.
Electing shareholders could opt to receive a PUC distribution. This was achieved through a s. 86 exchange under the Alberta plan of arrangement of their common shares for (newly-created) Class A common shares of Strathcona, the receipt of the PUC distribution on their Class A common shares and the subsequent s. 86 exchange of those Class A common shares back for their original common shares. (In the brief interim, the common shares had been temporarily held in treasury by Strathcona rather than being cancelled.) The Class A common shares had identical attributes to the common shares, except that they were convertible into common shares and entitled to an additional day's notice of any shareholder meeting.
One or both of the following bases was identified for considering that s. 84(4.1) did not apply to the PUC distribution. First, the special distribution was paid in connection with the reorganization of Strathcona's business into a pure-play heavy oil company and the discontinuance of its Montney business segment. Second, it represented the one-time and prompt distribution of the proceeds received by the Company on the Montney asset sales.
Shareholders who did not elect to receive the PUC distribution retained their common shares and received an equivalent taxable dividend instead, which was subject to Part XIII tax in the case of non-residents.
Strathcona
An Alberta company whose shares are listed on the TSX and is now a pure-play heavy oil producer with operations focused on thermal oil and enhanced oil recovery.
Asset sales
As part of the reorganization of Strathcona's business into a pure-play heavy oil company and the discontinuance of its Montney business segment, Strathcona sold substantially all of its Montney assets pursuant to three separate transactions outside of the ordinary course of business. These transactions generated aggregate proceeds of $2.72 billion. It has been determined that $2.142 billion of such proceeds are in excess of its current needs.
Steps under Alberta Plan of Arrangement
- Strathcona's articles will be amended to create an unlimited number of Class A common shares (Class A common shares). I
- In the course of a reorganization of the capital of the Company, shareholders who, prior to the election deadline, elect to receive a return of capital (“Electing Shareholders”) will transfer all their common shares to Strathcona in exchange for the issuance by Strathcona of one Class A common share per common share (the “First Share Exchange”). The Class A common shares have identical attributes to the common shares, except that they are convertible into common shares and entitled to an additional day's notice of any shareholder meeting.
- The common shares so acquired by Strathcona will continue to be issued and shall be held temporarily by Strathcona. The stated capital of the transferred common shares will deducted from the stated capital of the Strathcona common shares, and the same or a lesser amount added to the stated capital of the newly issued Class A common shares. The common shares will continue without interruption to be listed for trading on the TSX, and the Class A common shares will be listed on the TSX concurrently with their issuance.
- The stated capital of the Class A common shares will be reduced by the Return of Capital Amount of $10 per share for the purpose of distributing the same to holders of Class A common shares, i.e., all Electing Shareholders.
- A dividend on the common shares of $10 per share will be declared and designated as an eligible dividend for purposes of the Income Tax Act (the “Tax Act”) with such payment to be made to holders of common shares, i.e., all non-Electing Shareholders other than the Company.
- In the course of the reorganization of the capital of the Company, each Electing Shareholder will transfer their Class A common shares to Strathcona for cancellation in exchange for one common share of the Company held by Strathcona (see 3 above) (the “Second Share Exchange”). Strathcona will transfer the stated capital of the Class A to the common shares.
- Strathcona's articles will be amended to delete the initial amendments made to its authorized capital, such that its articles, as so amended, will read as they did immediately before the effect of the amendments.
Canadian tax consequences to Electing Shareholders
First Share Exchange
Such exchange is expected to occur on a s. 86 rollover basis.
Return of Capital distribution
The Return of Capital Amount will reduce the paid-up capital (PUC) of the Class A common shares by an equivalent amount. Management has determined that the PUC per Class A common share will be in excess of the special distribution amount of $10 per share.
One or both of the following exceptions to s. 84(4.1) of the Tax Act will apply to such PUC reduction:
- The amount is paid on the winding-up, discontinuance, or reorganization of the corporation's business.
- The amount may reasonably be considered to be derived from proceeds of disposition realized by the corporation from a transaction that occurred outside the ordinary course of its business within the period that commenced 24 months before the payment, and no amount that may reasonably be considered to be derived from those proceeds was paid by the corporation on a previous reduction of PUC in respect of any class of shares of the corporation.
In particular, the special distribution, including the Return of Capital Amount: is being paid in connection with the reorganization of Strathcona's business into a pure-play heavy oil company and the discontinuance of its Montney business segment; and is derived from the proceeds received by the Company on the asset sales.
The amount received as a return of capital on the Class A common shares will not be included in computing the holder's income and will reduce the ACB of such shares.
Second Share Exchange
Such exchange is expected to occur on a s. 86 rollover basis.
Non-Resident Electing Shareholders
For non-resident Electing Shareholders, the above consequences should apply.
Canadian tax consequences of special distribution as a dividend (non-Electing Shareholders)
For resident non-Electing Shareholders, this will be treated as a dividend subject to any application of s, 55(2). For non-residents, the amount of the dividend will be subject to withholding tax.
U.S. tax consequences
The receipt of Class A common shares from the Company in exchange for common shares pursuant to the First Share Exchange and the subsequent transfer pursuant to the Second Exchange of such Class A common shares in exchange for the same number of common shares is expected to be disregarded for U.S. tax purposes given their transitory nature.
The amount of the distributions generally will be includable in a U.S. holder's income as foreign source dividend income to the extent paid out of the company's current or accumulated earnings and profits. As the Company does not intend to calculate its current or accumulated earnings and profits for U.S. federal income tax purposes, a U.S. holder should therefore assume, subject to the discussion below, that the special distribution will be treated as a dividend for U.S. federal income tax purposes.
The special distribution derived from the proceeds received from the asset sales could be treated as a distribution in partial liquidation of the company pursuant to Code s. 302(e), in which case such distribution would be treated as a partial redemption of the common shares to a non-corporate U.S. holder.
Kinder Morgan
Overview
As a result of its indirect 30% interest in the Trans Mountain pipeline system, Kinder Morgan realized $1.2 billion on the sale of the system to the federal government for $4.5 billion. Kinder Morgan will distribute that sum to its shareholders as a stated capital (and paid-up capital) distribution. The exclusion from deemed dividend treatment under s. 84(4.1) for a one-off distribution of recently-received sales proceeds is being relied upon. The stated capital reduction (of $1.45 billion) exceeds the $1.2 billion stated capital distribution amount, so that the stated capital of the shares will be reduced to approximately $0.33 billion. This is being done in order to not be subject to potential solvency test restrictions under ABCA in declaring dividends.
Transaction
On May 29, 2018, the Company entered into a share and unit purchase agreement (the ‘‘Purchase Agreement’’) among Kinder Morgan Canada Cochin ULC (“KMCU”), the federal government (the ‘‘Purchaser’’), the Company and Kinder Morgan, Inc. (“KMI”), under which the Purchaser agreed to buy certain entities indirectly held by the Company, including the owner of the Trans Mountain pipeline system and related expansion project, for cash consideration of CDN$4.5 billion, subject to certain adjustments (the ‘‘Transaction’’). The Transaction was completed on August 31, 2018. The Company holds an approximate 30% indirect interest in KMCU, representing an interest in net proceeds of approximately $1.2 billion from the Transaction, after deductions for capital gains taxes, repayment of indebtedness and customary purchase price adjustments, and KMI indirectly holds the remaining approximately 70% interest in KMCU, representing an interest in net proceeds of approximately $2.8 billion from the Transaction, after such deductions.
Stated capital reduction
The stated capital account of the Restricted Voting Shares of the Company is to be reduced by $1.45 billion pursuant to s. 38(1) of the ABCA, for the purposes of (i) effecting a distribution to holders of Restricted Voting Shares by way of a return of capital of $1.2 billion, or approximately $11.40 per share (the “Return of Capital”), and (ii) providing the Company with additional flexibility to pay dividends in the future by way of a further reduction of $0.25 billion. Following such reduction, the stated capital account of the Restricted Voting Shares will be equal to approximately $0.33 billion.
Equivalent distribution on LP units
An equivalent distribution of an amount expected to be approximately $11.40 per Class B LP Unit, will be paid to KMI (indirectly through KMCC and KM Canada Terminals) in accordance with the equivalency provisions of the constating documents of the Company and its direct and indirect subsidiaries.
Purpose of additional $0.25B reduction
The purpose of the above additional reduction is to reduce the aggregate of the Company’s liabilities and stated capital of all classes of its shares so as to increase the difference between such amount and the realizable value of the Company’s assets, thereby providing the Company with additional flexibility to pay dividends if, as and when declared by the Board.
Share Consolidation
The restricted voting shares will be consolidated on the basis of one post-consolidation share for every three pre-consolidation shares.
Canadian tax consequences
Return of Capital distribution and s. 84(4.1)
The proceeds for the Return of Capital were derived from the Transaction. Management is of the view that the Return of Capital can reasonably be considered to have been derived from proceeds of disposition realized by a person or partnership in which the Company has a direct or indirect interest from a transaction that occurred outside the ordinary course of business of that person or partnership and, as a result, s. 84(4.1) should not apply to deem the amount paid to holders of Restricted Voting Shares of the Return of Capital to be a dividend. This determination is not free from doubt and no legal opinion or advance tax ruling has been sought or obtained.
Treatment of Return of Capital distribution as PUC reduction
The amount that will be paid by the Company to the Shareholders on the Return of Capital on the Restricted Voting Shares will not exceed the PUC of such shares. Based on historical trading prices for the Restricted Voting Shares since the Company’s initial public offering, which ranged from $14.93 to $20.00, Resident Holders are not expected to realize a capital gain as a result of the Return of Capital.
Additional stated capital reduction
The amount by which the Stated Capital Reduction exceeds the Return of Capital will have no immediate Canadian income tax consequences to a Shareholder nor will it affect the Shareholder’s adjusted cost base of the Restricted Voting Shares. Such reduction may have an effect in the future, in certain circumstances, including if the Company makes a distribution to shareholders or is wound-up, or if the Company redeems, cancels or acquires its Restricted Voting Shares.
Share Consolidation
In general, a Resident Holder will not realize a capital gain or a capital loss as a result of the Share Consolidation.
U.S. tax considerations
Return of Capital
The gross amount that will be paid by the Company to the U.S. Holders on the Return of Capital (including the amount of taxes withheld therefrom, if any) generally will be includable in a U.S. Holder’s gross income as dividend income on the date of receipt by the U.S. Holder, but only to the extent that such amount would be paid out of the Company’s current or accumulated earnings and profits as determined under U.S. federal income tax principles.
Share Consolidation
The Share Consolidation is intended to qualify as a ‘‘recapitalization’’ under s. 368(a)(1)(E). On that basis a U.S. Holder should not recognize any gain or loss for U.S. federal income tax purposes as a result of the Share Consolidation.
PFIC status
Based on the current and anticipated composition of the income, assets and operations of the Company and its subsidiaries, the Company believes it should not be a PFIC for the current taxable year or in future years.
Sierra/Cautivo Mining
Overview
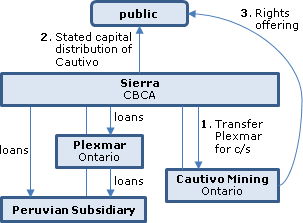
Sierra is proposing to effect a stated capital distribution of a Newco subsidiary (i.e., Cautivo Mining, which indirectly holds a Peruvian exploration company) to its shareholders in reliance primarily on the exception in ss. 84(4.1)(a) and (b) from deemed dividend treatment, although a nod is also given to the s. 84(2) exception. The disclosure relies on the proposition that the Newco shares will be issued to Sierra immediately before the distribution in exchange for transferring Sierra’s existing subsidiary to Newco, so that what will be distributed will represent proceeds of disposition. Newco will be making a rights offering immediately after the distribution in order to raise cash from its new shareholders.
Sierra
A CBCA mining company producing (through subsidiaries) precious and base metals from its Yauricocha Mine in Peru, and its Bolivar Mine and Cusi Mine in Mexico. Its common shares (the ”Sierra Shares”) trade on the Lima Stock Exchange and the TSX.
Cautivo Mining
The Corporation was incorporated under the OBCA on December 6, 2016. Its head office is in Lima Peru. Following the Reorganization (described below), Plexmar will hold 99.99% of the shares of Sociedad Minera San Miguelito S.A.C., being a Peruvian corporation holding the Las Lomas Project, located in the Department of Piura in northern Peru.
Plexmar
A wholly-owned Ontario subsidiary of Sierra holding 99.99% of the shares of Sociedad Minera San Miguelito S.A.C. (Peru).
Reorganization
Immediately prior to the Distribution Record Date, Sierra will transfer to Cautivo Mining all of the outstanding shares of Plexmar and loans owing to it by Plexmar and its subsidiary.
Capital distribution of (Cautivo Mining) Distributed Shares
Sierra is distributing to holders (other than Ineligible Holders as described below) of its common shares (the "Sierra Shares") of record as at 4:59 p.m. (Toronto time) on ●, 2017 (the "Distribution Record Date"), as a return of capital (the "Distribution"), all of the common shares (the "Distributed Shares") of its wholly-owned subsidiary, Cautivo Mining. The Distributed Shares will be distributed on the basis of one Distributed Share for every ● Sierra Shares held on the Distribution Record Date. Sierra Shares will begin trading on an ex-distribution basis on the the TSX two trading days before the Distribution Record Date, meaning that persons who acquire Sierra Shares on or after such date will not be entitled to receive the Distribution.
Rights offering to new holders of (Cautivo Mining) Distributed Shares
Immediately following the Distribution, the Corporation will issue to holders of its Distributed Shares (other than Ineligible Holders) at 5:00 p.m. (Toronto time) on the Distribution Record Date, being the "Rights Offering Record Date"), ● rights for each Distributed Share held (the "Rights Offering"). For each whole right (a "Right") held, a holder will be entitled to subscribe for one common share of the Corporation (a "Share") at a price of $● per Share (the "Subscription Price") at any time from ●, 2017 to 5:00 p.m. (Toronto time) (the "Rights Expiry Time") on ●, 2017 (the "Rights Expiry Date"). Holders who exercise their Rights in full are entitled to exercise additional Rights to acquire, at the Subscription Price, “Additional Shares” of Cautivo Mining on a pro rata basis (but subject to proration) (the “Additional Subscription Privilege.”) The aggregate number of Additional Shares available for subscription under the Additional Subscription Privilege will be the difference, if any, between the total number of Shares issuable upon exercise of Rights and the total number of Shares subscribed and paid for pursuant to the exercise of the basic subscription privilege.
Standby Agreement
The “Standby Purchasers” (Arias Resource Capital Fund II L.P. and Arias Resource Capital Fund II (Mexico) L.P.) have agreed, severally and subject to stipulated conditions, that each of the Standby Purchasers will purchase its respective percentage of the shares that are not subscribed under Rights Offering.
Listing
The Corporation has applied to list its Shares on the CSE.
Sale of Shares of Ineligible Holders
Sierra has made arrangements to have the those holders who are resident in a jurisdiction that would require the filing of a registration statement , prospectus etc. (“Ineligible Holders”) respecting the Distribution to have their ineligible shares and Rights (“Ineligible Securities”) issued to Computershare as custodian for the Ineligible Holders and has further arranged for the sale of such securities, and the net cash proceeds thereof, if any, to be distributed by Computershare to the Ineligible Holders on whose behalf such Ineligible Securities were issued.
Canadian tax consequences
S. 84(2) distribution
S. 84(2) provides, in effect, that a distribution made on a "winding up, discontinuance or reorganization of its [Sierra's] business", will not be taxed as a dividend so long as the amount or value of the funds or property distributed does not exceed the amount by which the PUC of the relevant shares is reduced on the distribution. It is noted that the Distribution is being made by Sierra as part of a number of potential changes, including the Reorganization, that are contemplated in order to maximize the overall value of the Sierra assets for Sierra Shareholders.
S. 84(4.1) distribution
S. 84(4.1) applies in certain circumstances to deem a return of capital by a public corporation (such as Sierra) to be a dividend. However, s. 84(4.1) does not apply to the Distribution provided that: (i) the Distribution can reasonably be considered to have been derived from proceeds of disposition realized by Sierra from a transaction that occurred outside the ordinary course of the business of Sierra but within the period that commenced 24 months before the Distribution; and (ii) no other amount that may reasonably be considered to have derived from such proceeds was paid by Sierra as a reduction of PUC prior to the Distribution. Management of Sierra has determined that the Distribution will be paid as a direct result of the proceeds of disposition that Sierra received on the sale of the outstanding Plexmar shares and loans to the Corporation in exchange for Shares under the Reorganization, that such transaction was outside of the ordinary course of Sierra's business, and that no amount that may reasonably be considered to have derived from such proceeds will have been paid by Sierra as a reduction of PUC prior to the Distribution. Therefore, the Distribution should be treated as a tax-free return of PUC (subject to any negative ACB issues) and not as a deemed dividend pursuant to s. 84(4.1).
Rights Offering
Generally, no amount will be required to be included in computing the income of a Resident Holder as a consequence of acquiring Rights under the Rights Offering..
Exercise of Rights
The exercise of Rights will not constitute a disposition of property for purposes of the Tax Act and, consequently, no gain or loss will be realized by a Resident Holder upon the exercise of Rights. Shares acquired by a Resident Holder upon the exercise of Rights will have a cost to the Resident Holder equal to the aggregate of the Subscription Price paid plus the adjusted cost base (if any) to the Resident Holder of the Rights exercised to acquire such Shares.
Brilliant Resources

Return of Capital
The stated capital account maintained by the Corporation in respect of its Common Shares will be reduced by an amount equal to $0.145 multiplied by the number of Common Shares issued and outstanding as at the Return of Capital Record Date. The aggregate of the Reduction of Stated Capital is expected to be approximately $21.13 million, based on the number of Common Shares issued and outstanding as at the date of this Information Circular. However, the Corporation's expectation is that 3,850,000 additional Common Shares will be issued, pursuant to the exercise of stock options.
The Corporation
A TSXV-listed Alberta corporation with 149.6M common shares outstanding, whose principal asset was a 100% investment in the Subsidiary.
The Subsidiary
Ivory Resources Inc., a Caymans company which formerly engaged in exploration in Equatorial Guinea. Following a request made by the Subsidiary for arbitration by the International Chamber of Commerce, on January 22, 2015 it reached an agreement with the Government of Equatorial Guinea to relinquish all its rights under the terms of an Exploration Services Agreement in exchange for U.S.$31.5M.
Investments
As at May 1, 2015, the Corporation had available funds and investments of $44,720,000. This is comprised of the Ram Power Investment and cash and cash equivalents of $34,720,000. The Corporation intends to use its available funds to fund the Return of Capital, to invest in each of equity, debt instruments and other investments as part of its focus as an investment issuer and for general and administrative expenses. The Corporation currently intends to make investments of up to $10 million in the next 12 months.
Ram Power Investment
. On April 30, 2015, the Corporation announced it had completed an investment in Ram Power, a renewable energy company listed on the TSX, as part of the approximately $74 million subscription receipt financing by Ram Power.
COB
The proposed COB, which constitutes a Change of Business pursuant to the policies of the TSXV, has been conditionally approved by the TSXV. Upon completion of the proposed COB, the Corporation's primary focus will be to seek superior returns by making investments in equity, debt or other securities of publicly traded or private companies or other entities, providing financing in exchange for pre-determined royalties or distributions and the acquisition of all or part of one or more businesses, portfolios or other assets.
Canadian income tax consequences
Management has determined that the amount of the Return of Capital will be less than the paid-up capital of the Common Shares for ITA purposes. S. 84(4.1) does not apply to the Return of Capital, provided that (i) the Return of Capital can reasonably be considered to have been derived from proceeds of disposition realized by the Corporation (or by a person in which the Corporation had a direct or indirect interest at the time the proceeds were realized, such as the Subsidiary) from a transaction that occurred outside the ordinary course of the business of the Corporation (or the Subsidiary) but within the period that commenced 24 months before the Return of Capital, and (ii) no other amount that may reasonably be considered to have derived from such proceeds was paid by the Corporation as a reduction of paid-up capital prior to the Return of Capital. Therefore, the Return of Capital should be treated as a tax-free return of paid-up capital (subject to there being a reduction of the adjusted cost base of the Common Shares) and not as a deemed dividend pursuant to subsection 84(4.1).
Goldcorp/Probe

Overview
After rolling its exploration assets (the "New Probe Assets") into a new Ontario subsidiary (New Probe), so that it will still retain the Borden gold project, Probe will distribute its common shares of New Probe to its shareholders as a paid-up capital distribution. Also occurring under an Ontario Plan of Arrangement will be an exchange of all the Probe common shares (other than of dissenters) for Goldcorp common shares (together with nominal cash so as to require a joint s. 85(1) election to achieve Canadian rollover treatment), with Goldcorp then dropping its Probe shares into a wholly-owned subsidiary ("Subco") and causing their amalgamation (with Subco as the survivor.) The former Probe shareholders will now hold 1.6% of the Goldcorp shares (as well as 100% of New Probe). The share exchange and amalgamation is intended to qualify as a forward triangular merger - although Probe is believed to be and have been a PFIC and Goldcorp is believed not to be a PFIC, so that Code rollover treatment generally would not be available as per a proposed retroactive Regulation.
See summary under Mergers & Acquisitions - Shares for Shares and Nominal Cash.
| Locations of other summaries | Wordcount | |
|---|---|---|
| Tax Topics - Public Transactions - Mergers & Acquisitions - Mergers (mostly Plans of Arrangement) - Shares for Shares and Nominal Cash | Spin-off by Probe Mines of New Probe and acquisition of Probe Mines by Goldcorp for shares and nominal cash in forward triangular merger | 1169 |
Chalice/Coventry

Overview
Under a BC Plan of Arrangement, Coventry is to transfer most of its subsidiaries (the "Targets") to Western Rift (a subsidiary of Chalice) in consideration for Chalice shares, which Coventry will then transfer to its shareholders as a stated capital distribution. The Arrangement is expected to result in the Coventry shareholders holding 15.46% of the Chalice shares, and in Coventry holding only cash and a project in Alaska.
See detailed summary under Cross-Border Acquisitions – Inbound – Asset sale/share distribution.
| Locations of other summaries | Wordcount | |
|---|---|---|
| Tax Topics - Public Transactions - Mergers & Acquisitions - Cross-Border Acquisitions - Inbound - Asset sale/share distribution | Chalice Gold acquisition of Coventry Resources assets for shares, followed by share distribution | 242 |